Two friends, Priya and Mark, both want a comfortable retirement. They save the same amount each year, and their investments earn the same return. The only difference between them is when they start.
Meet the two savers
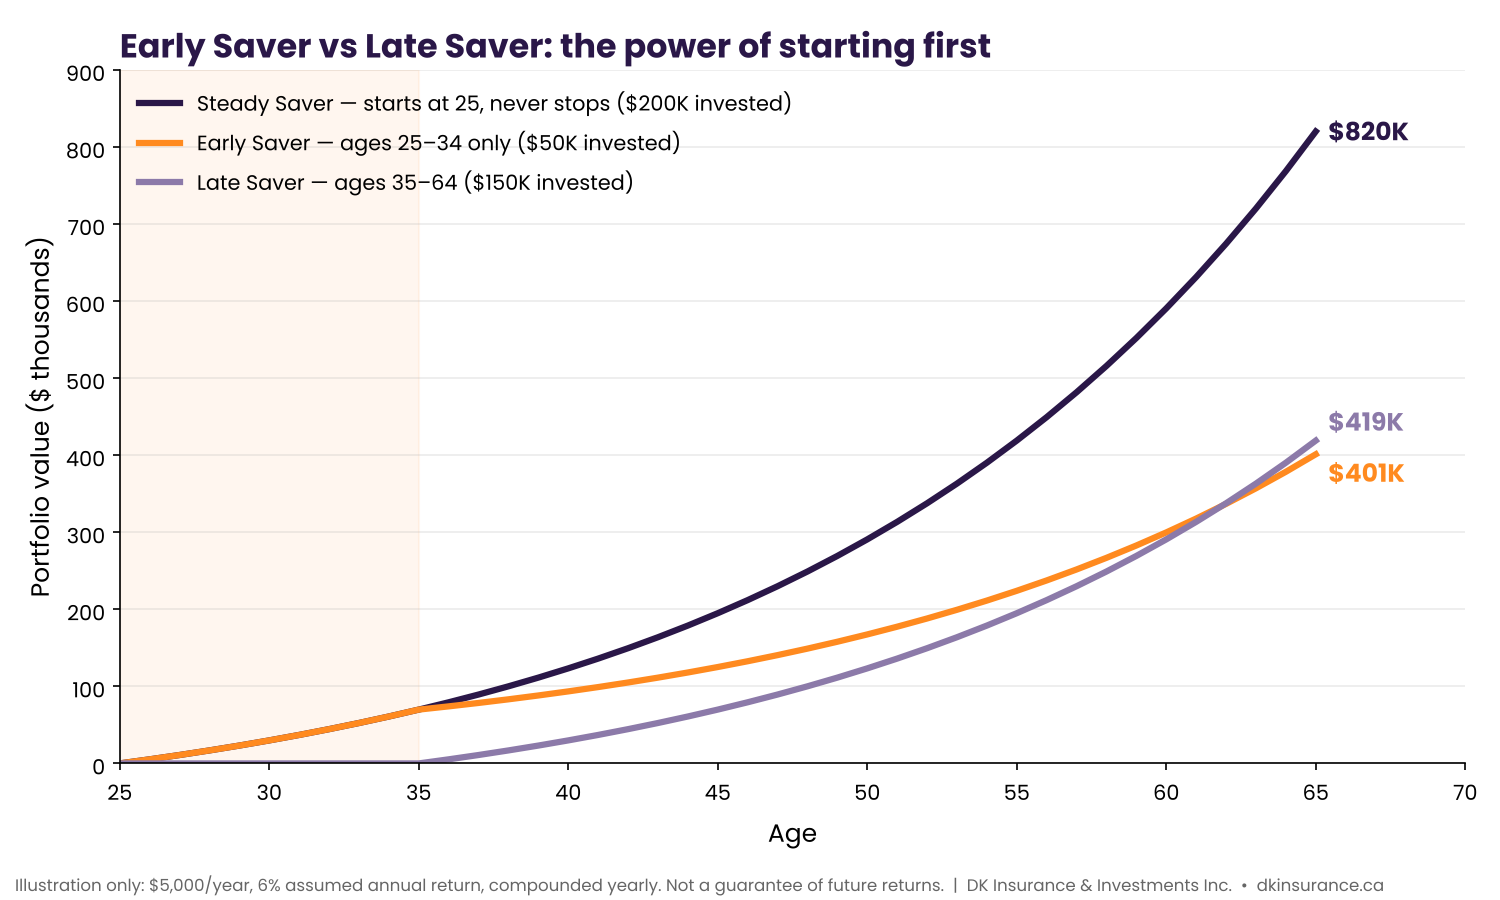
Priya, the early saver, starts investing $5,000 a year at age 25. After 10 years, at 35, she stops completely and never adds another dollar. Total she puts in: $50,000.
Mark, the late saver, waits until age 35 and then invests $5,000 a year for 30 years, all the way to 65. Total he puts in: $150,000.
Both earn an assumed 6% a year. Who has more at 65?
The result
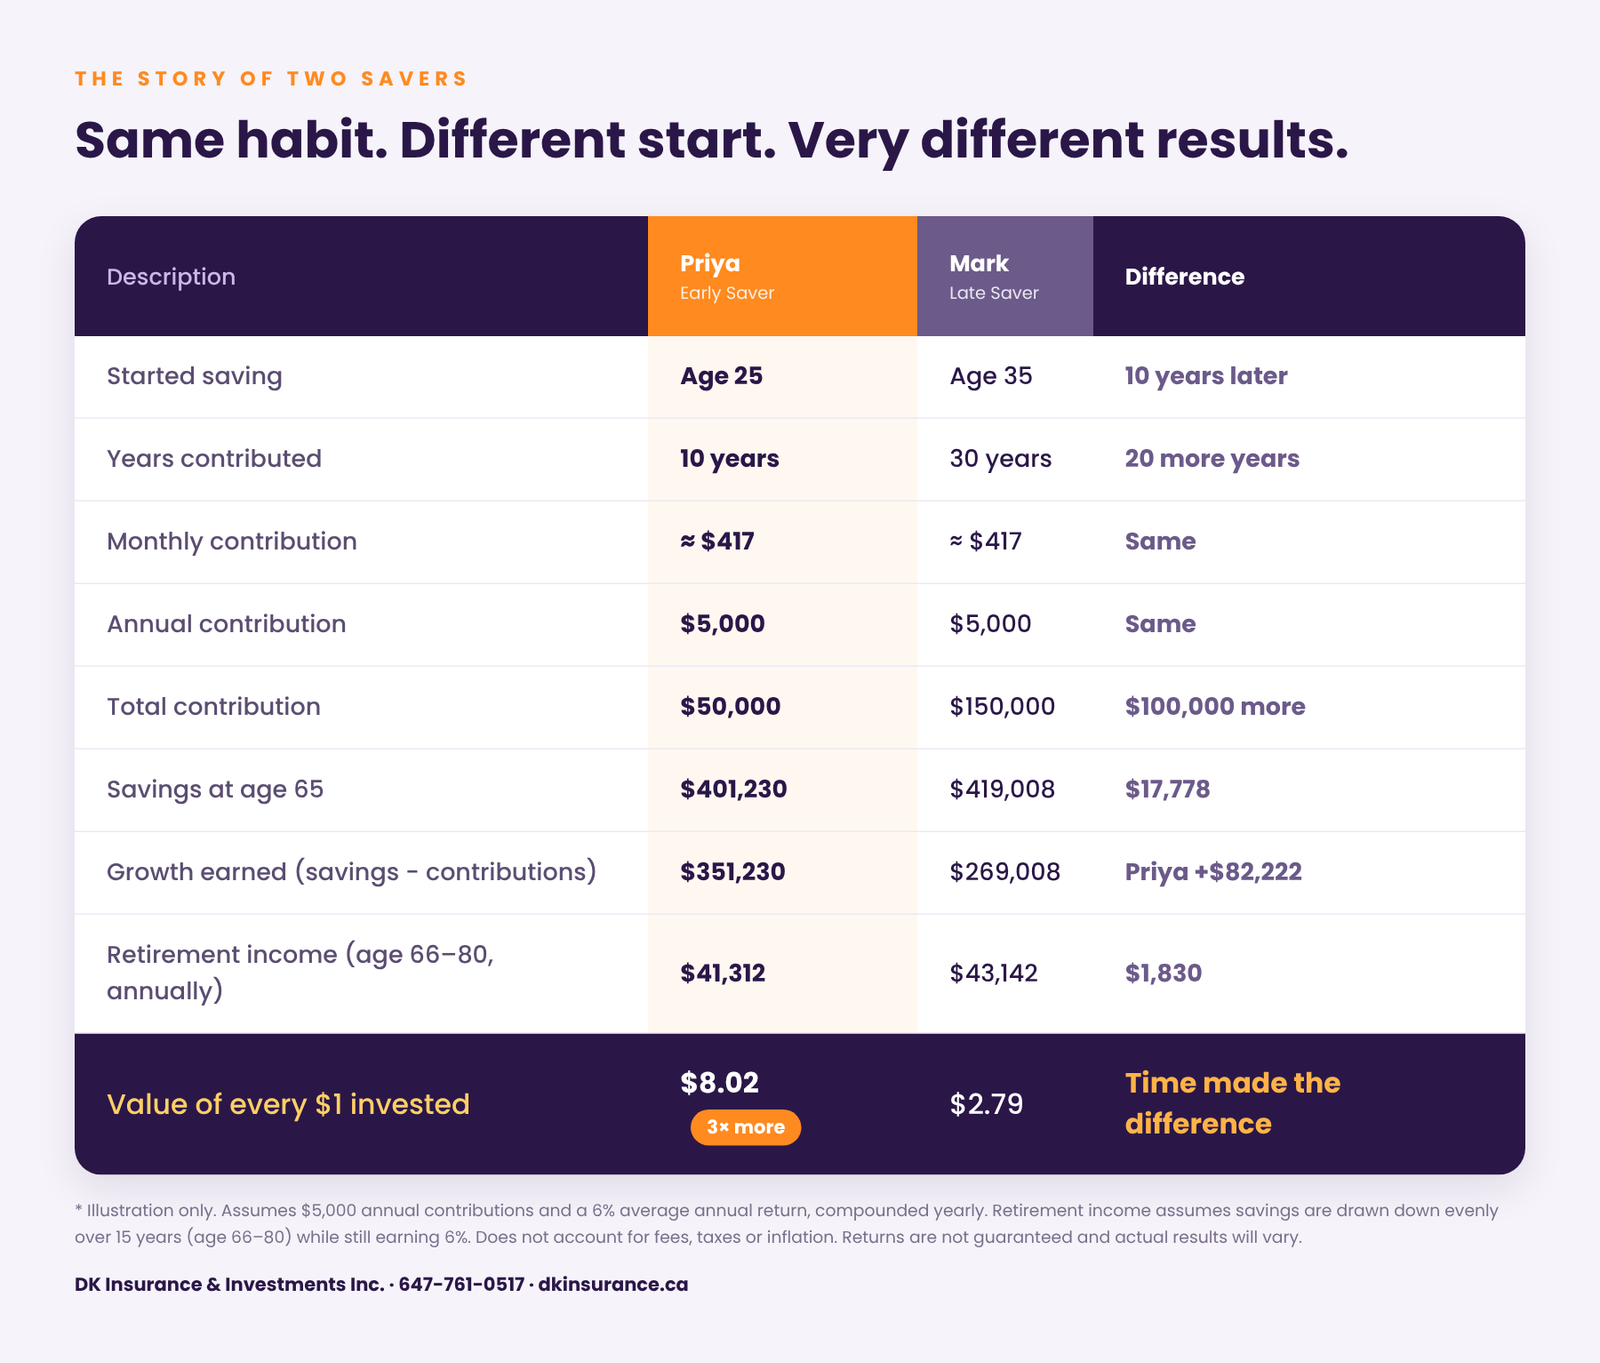
Mark had to put in three times as much money to end up in about the same place as Priya.
Priya’s money compounded for 30 more years after she stopped saving. Her savings kept earning, and then the earnings themselves kept earning.
What if you start early and never stop?
Meet the steady saver. She starts at 25, invests $5,000 a year and keeps going until 65. She puts in $200,000 and ends up with about $820,000. That’s roughly double either Priya or Mark.
The real cost of waiting
Suppose your goal is $1 million by age 65, with a 6% return. Here is roughly what you’d need to invest each month, depending on when you start:
- Start at 25: about $500 a month
- Start at 35: about $1,000 a month
- Start at 45: about $2,160 a month
Each 10 years you wait roughly doubles the monthly amount you need.
“But I’m already 35, 45 or 50”
That’s okay. Compound growth works from whatever day you start. A late start beats no start, and the right plan can help you catch up. For example, you can make full use of your RRSP to get a tax deduction, grow money tax-free in a TFSA, and increase your contributions as your income grows.
3 simple steps to start this month
- Automate it. Set up a monthly contribution, even $100–$200. If it comes out automatically, you never have to remember.
- Use the right account. Your TFSA, RRSP and (for first-time home buyers) FHSA each work differently. Picking the right one can add years of tax-sheltered growth.
- Protect the plan. A savings plan only works if it can keep going. Life and critical illness insurance make sure an unexpected event doesn’t wipe out years of saving for your family.
Let’s build your plan
Whether you’re 25 or 55, the best time to start was yesterday, and the second-best time is today. Book a free, no-pressure review with DK Insurance & Investments Inc. We’ll look at where you are, where you want to be and how to get there.
📞 Call/text 647-761-0517 | 🌐 dkinsurance.ca | Serving families across Ontario
Disclaimer: This is an illustration only. It assumes $5,000 annual contributions and a 6% annual return, compounded yearly, and does not account for fees, taxes or inflation. Actual returns vary and are not guaranteed. Past performance does not guarantee future results. This article is for general information and is not personalized financial advice. Speak with a licensed advisor about your situation.